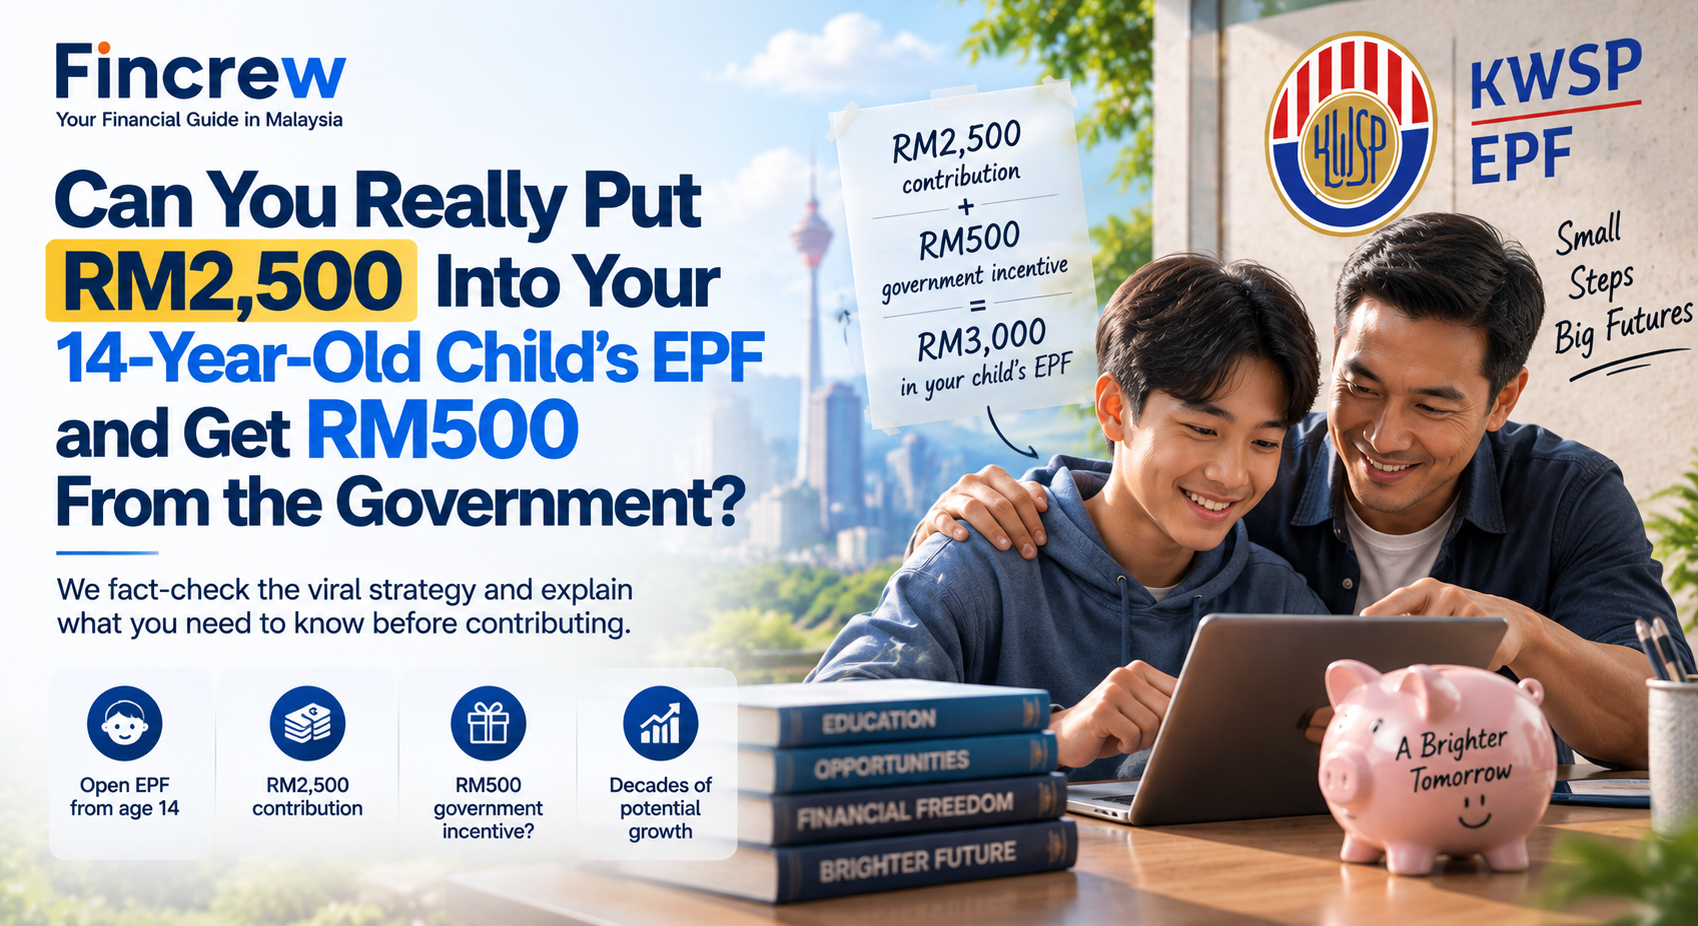

A Malaysian parent recently shared an interesting money strategy on social media: once his child turned 14, he opened an EPF account, registered for i-Saraan and planned to contribute RM2,500.
The attraction is obvious. Under the current i-Saraan incentive, RM2,500 could qualify for a RM500 government incentive, effectively putting RM3,000 into EPF before considering future dividends.
Sounds like a fantastic head start for a teenager.
But before every Malaysian parent rushes to open an EPF account for their 14-year-old, there is one very important detail to understand.
Being old enough to open an EPF account does not automatically mean your child qualifies for i-Saraan.
Yes, You Can Have an EPF Account From Age 14
This part of the social media post checks out.
EPF states that the minimum age to register and contribute as an EPF member is 14 years old. Malaysian citizens and permanent residents can also register through the KWSP i-Akaun app, with e-KYC available for identity verification. (KWSP)
So technically, your teenager doesn’t need to wait until getting their first full-time job to have an EPF account.
And from a long-term savings perspective, starting at 14 creates something extremely valuable: time.
But opening an EPF account and qualifying for the government’s i-Saraan incentive are two separate matters.
Where Does the RM2,500 → RM500 Idea Come From?
The maths is correct.
For 2026, i-Saraan provides eligible members with a government incentive equal to 20% of their annual voluntary contributions, capped at RM500 per year.
That means:
| Annual Contribution | Government Incentive | Total Added |
|---|---|---|
| RM500 | RM100 | RM600 |
| RM1,000 | RM200 | RM1,200 |
| RM2,000 | RM400 | RM2,400 |
| RM2,500 | RM500 | RM3,000 |
| RM5,000 | RM500 | RM5,500 |
That’s why RM2,500 is the interesting number. EPF itself states that at least RM2,500 of annual contributions is required to receive the maximum RM500 incentive. (KWSP)
Putting in another RM2,500 wouldn’t generate another RM500 because you’ve already reached the annual incentive ceiling.
There’s also a lifetime limit. The standard i-Saraan government incentive is capped at RM5,000 over the member’s lifetime, or until age 60, whichever comes first, subject to the programme’s terms. (KWSP)
Here’s the Catch: i-Saraan Isn’t Simply a Bonus for Every EPF Member
This is the part that can easily disappear when a financial tip goes viral.
EPF describes i-Saraan as a voluntary contribution programme primarily designed for self-employed people and those without fixed income.
Current eligibility includes Malaysian EPF members below 60 who are self-employed with no fixed income, workers in the gig economy, and certain other eligible groups such as civil servants under pension schemes. (KWSP)
So this equation is misleading:
Turn 14 + Open EPF + Deposit RM2,500 = Free RM500
Age 14 establishes that someone can become an EPF member. It does not by itself establish i-Saraan eligibility.
A 14-year-old who genuinely meets i-Saraan’s requirements is a different situation from a parent simply opening an EPF account for a child who doesn’t.
That’s why parents shouldn’t contribute RM2,500 expecting RM500 purely because they saw someone else successfully do it.
Check the child’s i-Saraan eligibility with EPF first.
But Starting EPF at 14 Is Still an Interesting Idea
Even without focusing on the RM500 incentive, there’s something powerful about beginning retirement savings this early.
Suppose an eligible teenager ended up with RM3,000 in EPF at age 14 after a RM2,500 contribution and RM500 incentive.
What happens if that RM3,000 simply sits there for decades?
For illustration, let’s assume an average return of 5% per year. This is only a hypothetical calculation and is not a prediction of future EPF dividends.
By age 60, that RM3,000 could grow to roughly RM28,000 without another contribution being added.
That’s what 46 years can do.
The interesting lesson isn’t really the RM500.
It’s the 46 years.
Someone starting retirement savings at 14 has something a person starting at 40 can never buy back: decades of potential compounding.
What If You Did It Every Year?
This is where we need to be careful again.
You might see RM500 a year and think:
“Great. I’ll collect RM500 from the government every year until my child is 60.”
That’s not how the current incentive works.
The standard i-Saraan incentive has a RM5,000 lifetime maximum, subject to the programme rules. At today’s RM500 annual maximum, someone receiving the full incentive each year would reach that lifetime amount after 10 years. (KWSP)
Of course, they could continue making eligible EPF contributions after reaching the incentive ceiling. They simply shouldn’t calculate their retirement projections assuming another RM500 government incentive every year for the next four decades.
What About i-Saraan Plus?
There’s another programme that could cause confusion.
Beginning in 2026, i-Saraan Plus provides a higher incentive specifically for eligible e-hailing and p-hailing drivers.
The matching rate is also 20%, but the maximum is RM600 per year, with a lifetime ceiling of RM6,000 or until age 60, whichever comes first. Standard i-Saraan continues separately for eligible self-employed and informal-sector workers. (KWSP)
So don’t mix up screenshots or calculations for i-Saraan Plus with the normal i-Saraan programme.
Should Parents Open an EPF Account for Their Teenager?
There are two separate questions here.
Can a Malaysian start an EPF account at 14? Yes. EPF explicitly permits registration and contributions from that age. (KWSP)
Can every 14-year-old receive the RM500 i-Saraan incentive by depositing RM2,500? No such blanket entitlement appears in EPF’s eligibility rules. The member still needs to satisfy i-Saraan’s requirements. (KWSP)
That distinction is probably the most important takeaway from this entire viral strategy.
Parents should also remember what EPF is designed for: retirement. Putting money into a child’s EPF is very different from keeping the same RM2,500 in savings for university fees, their first car or other expenses they’ll encounter in their twenties.
Long-term money and short-term money have different jobs.
The Fincrew Take
The social media post contains a genuinely interesting idea, but the headline numbers need context.
RM2,500 → RM500 is real for an eligible i-Saraan member under the current rules.
EPF membership from age 14 is also real.
What isn’t safe to assume is that combining those two facts automatically makes every Malaysian 14-year-old eligible for the government incentive.
If your child genuinely qualifies, the numbers are certainly worth understanding. If they don’t, starting retirement savings early can still be valuable — just don’t make the contribution expecting a government bonus that may not apply.
And perhaps the biggest lesson isn’t about finding a RM500 “hack” at all.
It’s this:
RM500 is nice. Forty-six years of compounding could be far more powerful.
Before making the contribution, check your child’s current eligibility and registration status directly with EPF. Programme conditions can change, and once money is placed into retirement savings, it shouldn’t be treated like an ordinary savings account.
Disclaimer: This article is for general educational purposes only. i-Saraan eligibility, government incentives and EPF rules are subject to current terms and may change. Confirm eligibility directly with EPF before making a contribution.