
You have RM50,000 in your bank account. One day, you pass away unexpectedly.
Can your spouse simply withdraw the money? Can your children transfer it because they know your online banking password? Will the bank eventually keep it?
Generally, no.
Your money doesn’t disappear when you die, but it also doesn’t automatically become immediately available to your family. It becomes part of your estate and must be dealt with through the appropriate estate administration process.
Your Family Can’t Just Withdraw the Money
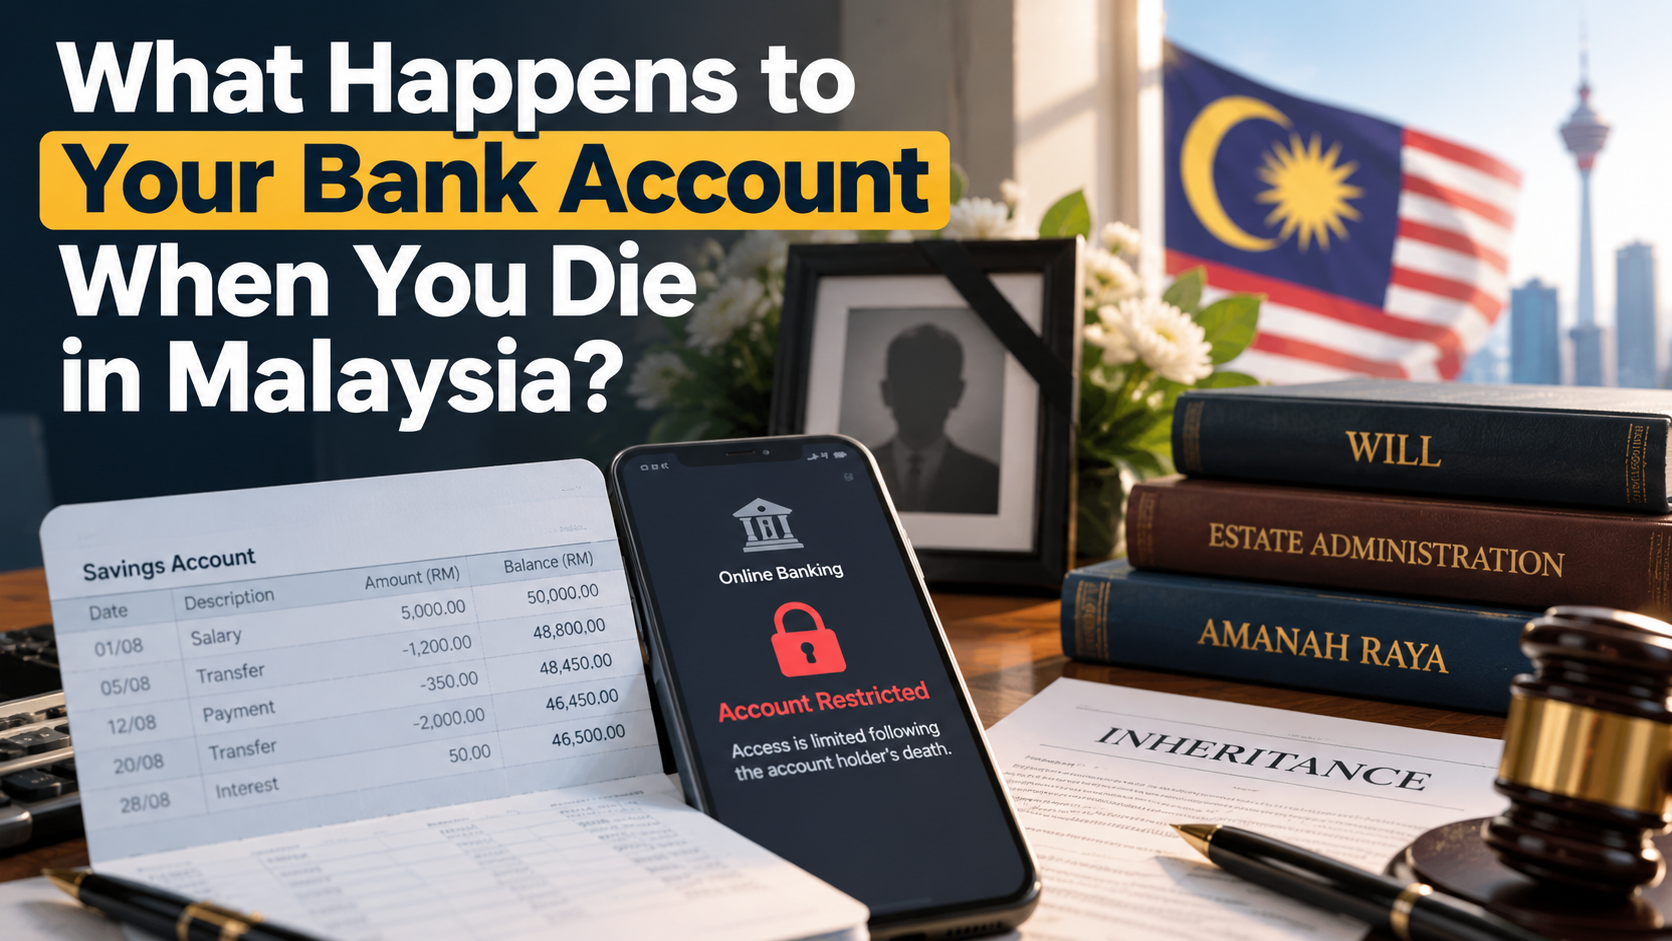
Once a bank is notified of an account holder’s death, an individually held account will generally be restricted while the estate is being administered.
Even if your wife knows your ATM PIN or your son knows your online banking password, that doesn’t give them legal authority to take the money.
The important question becomes: who is legally authorised to manage your estate?
If there’s a valid will, the named executor may need to obtain the appropriate authority, such as a Grant of Probate. Without a will, an administrator may need to be appointed instead. Malaysia also has different procedures for certain smaller estates.
In other words, the bank isn’t keeping your money. It’s waiting for the proper person to establish the legal authority to deal with it.
What If There’s Only RM20,000 or RM50,000?
A smaller bank balance doesn’t necessarily mean your family can simply collect it immediately.
Malaysia does, however, have simplified administration routes for certain estates. Current government guidance classifies movable-property-only estates worth up to RM600,000 as summary estates, which may be administered through Amanah Raya. Bank savings are one example of movable property.
So you don’t need to be a millionaire for estate planning to matter.
Someone leaving RM50,000 in a bank account can still leave paperwork behind for their family.
What About Joint Bank Accounts?
This can be different.
Depending on the particular bank account’s terms and applicable requirements, a surviving joint account holder may be able to continue dealing with the account or receive the remaining balance.
But don’t assume that every Malaysian joint account works exactly the same way. If you’re keeping emergency household money in a joint account specifically so your spouse can access it after your death, check your bank’s terms while you’re still around to ask the question.
Don’t Use Your Banking Password as an “Estate Plan”
A surprisingly common plan is:
“My wife knows my PIN, so it’s okay.”
It isn’t a proper estate plan.
Your family is better off knowing what assets you have and where they are held, rather than simply knowing your passwords.
Imagine someone today having money across Maybank, CIMB, GXBank, EPF, ASNB, investments and several other platforms. If they die without leaving a record, their family may not even know some of those assets exist.
A simple personal asset list can already make things much easier. Record your banks, investments, EPF, insurance or takaful, properties, vehicles, major debts and where your important documents or will are kept.
No passwords are necessary.
The Bigger Problem May Be Next Month’s Bills
This is the part many families don’t think about.
Suppose the husband handles most household finances and keeps RM100,000 in accounts under his name. He dies unexpectedly.
The family may eventually inherit that money — but the mortgage, electricity bill, groceries and children’s expenses don’t wait for the estate process to finish.
That’s why estate planning isn’t only about answering “Who gets my money when I die?”
You should also ask:
“Does my family have money they can access immediately if I’m suddenly gone?”
An appropriate household emergency fund, properly structured joint finances, insurance or takaful protection, nominations where applicable, and a proper will or estate plan can all form part of that preparation.
One Simple Thing You Can Do Tonight
Open your phone and list every place where you currently have significant money.
You may be surprised how long the list has become.
Then ask yourself: If I died tomorrow, would my family know all of these accounts exist?
If the answer is no, that’s probably the first thing worth fixing.
Because the biggest problem may not be whether your family eventually inherits your money.
It may be whether they can find it, claim it and survive financially while waiting for it.