
Think Capital Gains Tax only applies when your company sells shares and makes money?
Not anymore.
LHDN updated its Capital Gains Tax (CGT) Guidelines for Unlisted Shares on 21 September 2026, and one change could catch Malaysian business owners by surprise.
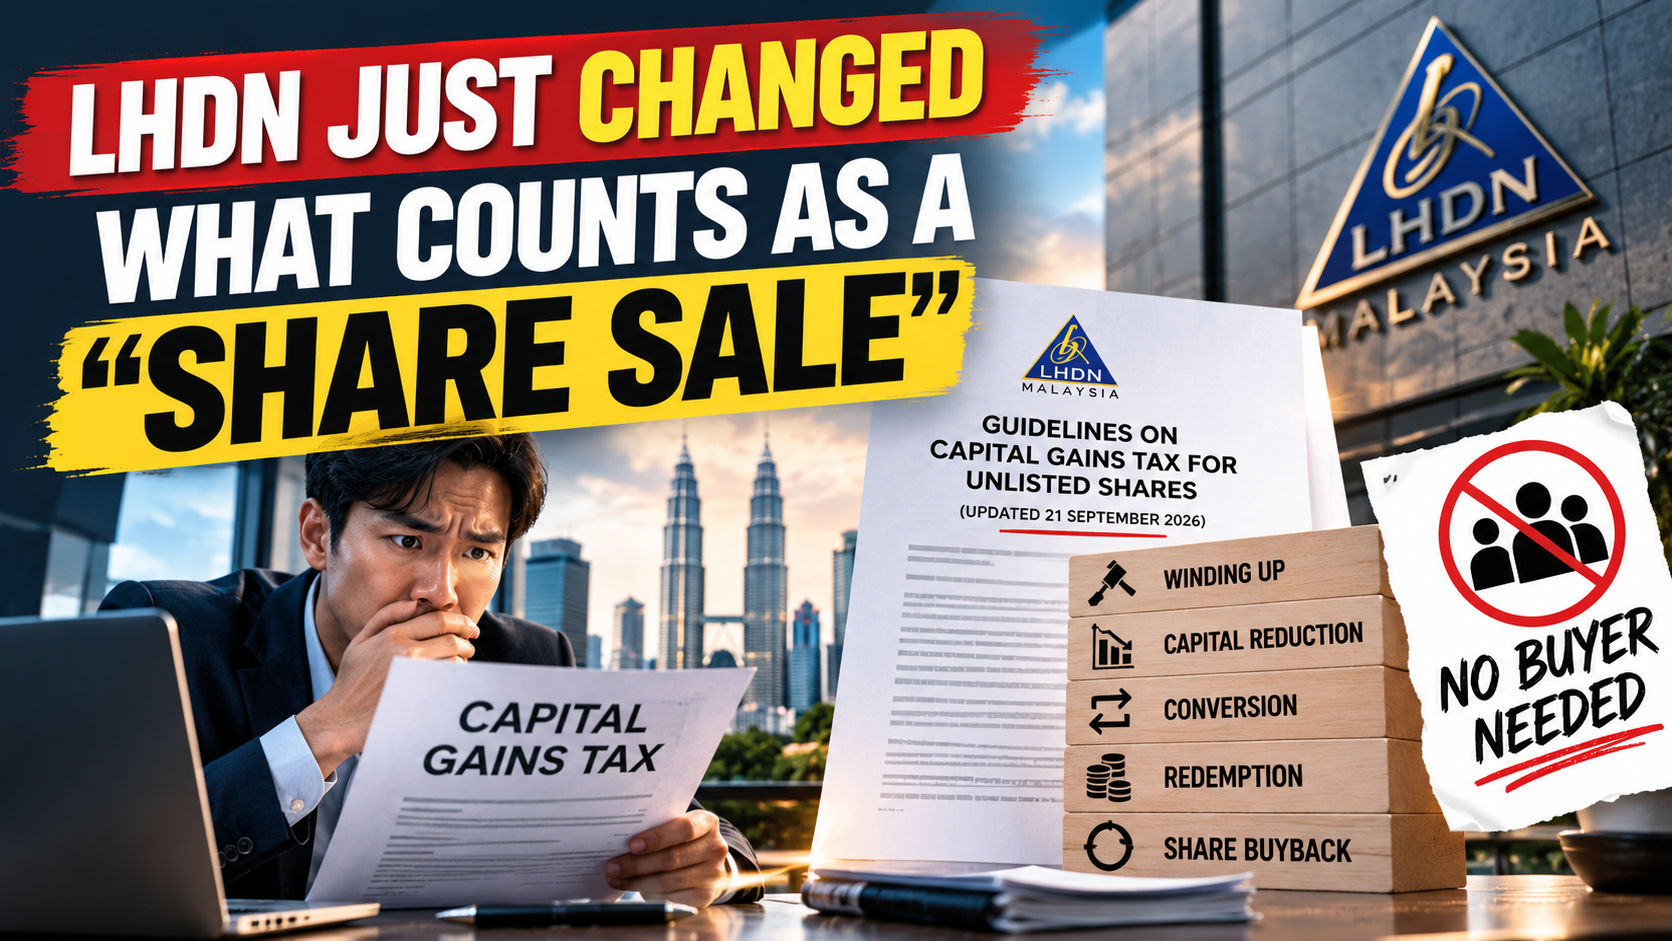
Your company could potentially have a “disposal” for CGT purposes even when there is no buyer and no normal share sale.
So What Changed?
Malaysia’s CGT rules affect relevant entities such as companies, LLPs, trust bodies and cooperatives disposing of unlisted shares.
Previously, most business owners would naturally associate a disposal with selling or transferring shares. But LHDN’s updated guideline makes the definition much wider.
Here’s the difference:
| What Happens? | Can It Count as a Disposal? |
|---|---|
| Sell shares | Yes |
| Transfer shares | Yes |
| Company buys back shares | Yes |
| Reduce share capital | Yes |
| Redeem shares | Yes |
| Convert shares | Yes |
| Shares/rights end during winding up | Yes |
| Company dissolved and ownership ends | Yes |
| Transfer shares to/from nominee | Generally no |
That means “we didn’t sell the shares” may no longer be enough to conclude that there is no CGT issue.
Closing a Company? This Is Where It Gets Interesting
Imagine your holding company owns shares in another private company.
The business is no longer needed, so you decide to wind it up.
There is no buyer. Nobody signs a normal sale agreement. You simply close the company.
Under LHDN’s updated guidance, the ending of rights over those shares through a winding up or dissolution can still constitute a disposal.
The same issue can arise with share redemptions, conversions, capital reductions and buybacks.
That doesn’t automatically mean tax will always be payable. The actual CGT position depends on the transaction, gains, exemptions and applicable rules.
But it means CGT should be checked before the corporate exercise is completed — not afterwards.
And You Only Have 60 Days
This is probably the number business owners should remember.
60 DAYS
The e-CKM generally has to be filed and any CGT due paid within 60 days from the disposal date.
The updated guideline also expands the timing rules to deal with situations where ownership or rights end rather than a normal sale taking place.
For winding ups, capital reductions, conversions, redemptions and buybacks, LHDN has separate guidance dealing with the applicable date and disposal price.
So if your accountant only looks at the CGT position after the restructuring is completed, your 60-day clock may already be running.
What About Nominee Shares?
There’s another useful clarification.
When a nominee sells shares, LHDN treats the disposal as belonging to the actual beneficial owner, so the tax responsibility follows the real owner.
However, simply transferring shares to a nominee — or transferring them back — is not treated as a disposal.
Why Business Owners Should Care
This isn’t only an accountant problem.
Business owners regularly close dormant companies, restructure groups, redeem investor shares, reduce capital or reorganise shareholdings.
These can look like ordinary corporate exercises.
But under the updated rules, some can potentially become CGT events even though nobody actually “sold” the shares in the everyday sense.
So before your company restructures, winds up, redeems shares or changes its share capital, add one question to the checklist:
“Will LHDN consider this a disposal?”
Better to ask before Day 1 than discover it on Day 59.